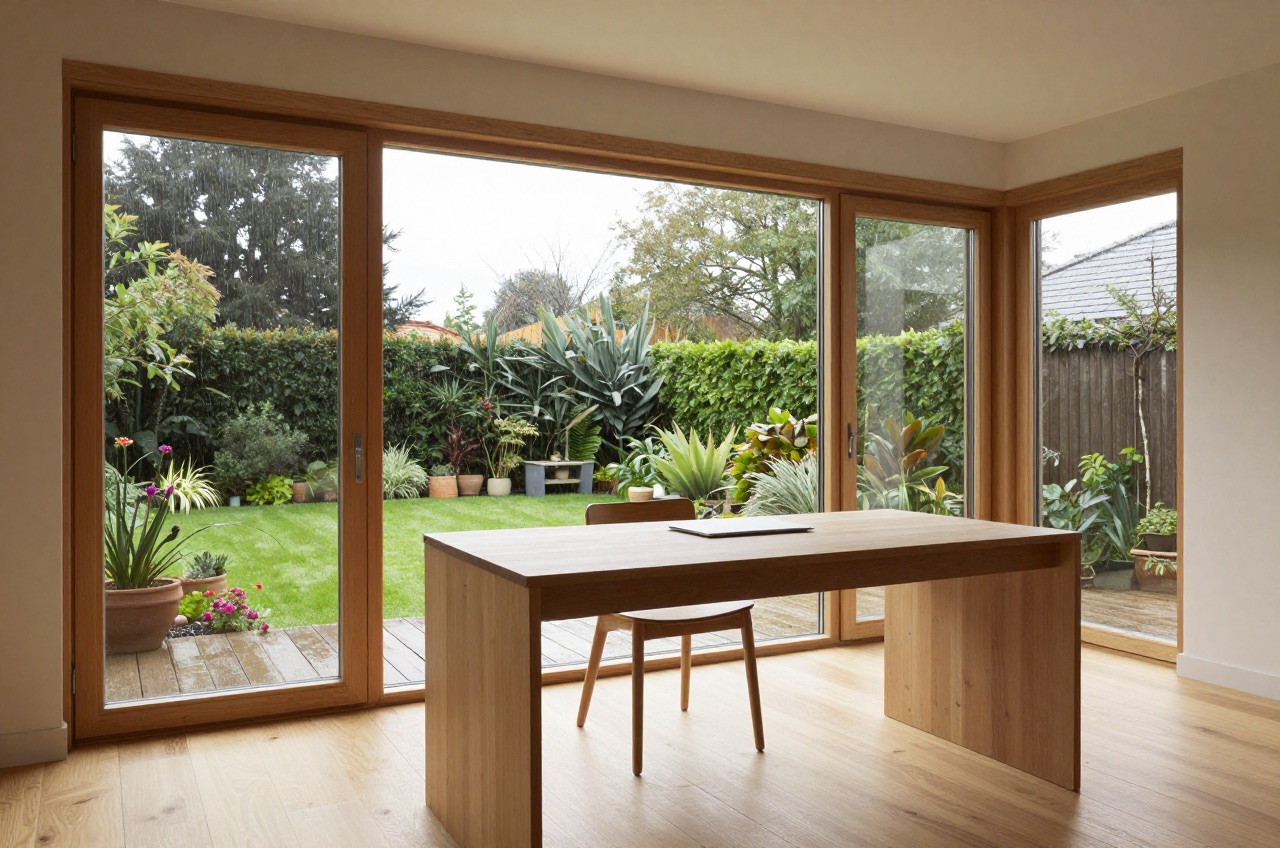
The terms “garden office” and “garden room” are often used interchangeably, but they describe structures built to meaningfully different specifications, and the distinction matters when you are spending £10,000 or more. A garden room is primarily a garden-facing social or hobby space, typically built to a lighter insulation standard. A garden office is designed for year-round professional use: better insulation, more electrical capacity, and acoustic performance that a video call demands.
Garden Room vs Garden Office: Key Differences
| Feature | Garden Room | Garden Office |
|---|---|---|
| Primary use | Gym, studio, bar, hobby space | Year-round remote working |
| Insulation (wall) | 50–75 mm (U-value ~0.5–0.8 W/m²K) | 75–100 mm+ (U-value ≤0.28 W/m²K) |
| Insulation (floor/roof) | Moderate | Full, thermally broken |
| Heating | Single fan heater or small radiator | Electric radiator or underfloor heating, thermostatically controlled |
| Electrical supply | 1–2 circuits | Dedicated sub-consumer unit, multiple circuits |
| Acoustic treatment | Usually none | Acoustic insulation in walls and floor |
| Broadband | Powerline adaptor or Wi-Fi | Ethernet feed from house recommended |
| Typical cost (3×3 m) | £8,000–£14,000 | £12,000–£20,000 |
The line between the two categories is blurring as manufacturers improve standard specifications. When comparing quotes, ask directly about U-values rather than relying on the marketing label.
Planning Permission
Most garden offices and garden rooms in England fall under Permitted Development (PD) for outbuildings and do not need a planning application, provided:
- The structure is in the rear or side garden, not forward of the principal elevation1
- Maximum height: 2.5 m if within 2 m of a boundary; elsewhere 4 m for a dual-pitch roof or 3 m for any other roof, with eaves no higher than 2.5 m1
- The ground covered by all buildings other than the original house (outbuildings and any extensions) does not exceed 50% of the land area around the original house1
- The structure is not used as separate residential accommodation (a self-contained annexe with sleeping/cooking/bathroom facilities loses PD status)1
Building Regulations are a separate matter from planning permission. Detached garden buildings up to 15 m² in floor area with no sleeping accommodation are exempt from Building Regulations.2 From 15 m² to 30 m², a building with no sleeping accommodation is exempt only if every part of it is at least 1 m from the boundary or it is built substantially of non-combustible materials.2 Above 30 m², Building Regulations always apply. Electrical work must comply with Part P regardless of building size, use an electrician registered with a competent person scheme such as NICEIC or NAPIT.3
Listed buildings and conservation areas: Permitted Development rights are restricted; always check with your local planning authority before proceeding.4
2026 UK Cost Guide
Prices below are fully installed (foundation, structure, electrical connection, internal finishes).
| Size | Garden Room | Garden Office (insulated, year-round) |
|---|---|---|
| 2.4×2.4 m | £6,000–£10,000 | £9,000–£14,000 |
| 3×3 m | £8,000–£14,000 | £12,000–£20,000 |
| 3×4 m | £10,000–£18,000 | £15,000–£25,000 |
| 4×5 m | £14,000–£25,000 | £20,000–£35,000 |
| 5×6 m (bespoke) | £20,000–£40,000 | £28,000–£50,000+ |
What drives the price:
- Cladding, Siberian larch and cedar are premium; treated softwood is the budget choice; Corten steel or aluminium adds 20–40%
- Glazing, double-glazed units are standard; triple glazing adds £800–£2,000 to a typical build
- Foundation type, screw pile foundations (fastest, minimal ground disturbance) cost £600–£1,400; concrete strip or raft foundations are cheaper per m² but require groundworks
- Electrical supply, a new armoured cable run from the house consumer unit costs £600–£1,500 depending on distance and route
Foundations
Screw pile foundations (helical steel piles, typically 8–12 per standard room) are now widely used for garden buildings. They can often be installed in a few hours, need no wet concrete and can be removed later. A ground survey is recommended if the site is on made-up ground, clay with significant shrink-swell potential, or within root-influence distance of mature trees.
Concrete pad or strip foundations remain appropriate for heavier structures or sloping sites. Allow £800–£2,000 for groundworks separate from the structure cost.
Insulation Standards to Ask For
To be comfortable year-round without an oversized heater, aim for:
- Walls: U-value of 0.28 W/m²K or better (equivalent to approximately 90 mm of high-performance PIR insulation between 90 mm studs)
- Roof: U-value of 0.18 W/m²K or better
- Floor: U-value of 0.22 W/m²K or better, with a thermally broken floor frame to prevent cold bridging
A building meeting these standards can usually be kept at 20°C with a 1–2 kW electric radiator through a typical UK winter. They are looser than a house extension has to be: Approved Document L asks new walls and floors in an existing home for 0.18 W/m²K and a new roof for 0.15.5
Electrical and Data Infrastructure
For a functional garden office, specify:
- Minimum 32 A armoured cable from the house consumer unit (allows for future EV charging or a heat pump if planned)
- A sub-consumer unit in the garden building with at least two circuits, one for sockets, one for lighting
- RCD and surge protection on all circuits
- Minimum four double sockets plus a dedicated desk circuit
- An external weatherproof socket on the outside wall
- A CAT6 Ethernet cable run inside the same conduit as the power cable during installation, far cheaper than retrofitting
Running Costs
An insulated 3×4 m garden office heated to 20°C during a standard working week (5 days, 9 hours per day) will typically consume 2–4 kWh per day in winter and under 0.5 kWh in summer. At the Ofgem price cap unit rate from 1 October 2026 (26.32p/kWh), 2–4 kWh a day across a 22-day working month is roughly £12–£23 a month in winter heating, broadly equivalent to heating a spare bedroom.6
Tax Treatment for Garden Offices
If you use a garden office wholly and exclusively for your business as a self-employed person, you may be able to claim capital allowances on fittings such as the electrical system, but not on the structure itself (HMRC treats even a demountable garden building as a building, not plant), and deduct running costs as a business expense.78 This is a complex area that depends on how the structure is treated under HMRC rules, speak to your accountant before making decisions based on tax treatment.
Should You Buy a Kit or Go Bespoke?
Kit/modular suppliers (multiple manufacturers offer panelised systems installed by their own teams) offer faster delivery (typically 6–16 weeks), fixed pricing, and predictable quality. Bespoke local joiners and landscaping contractors can offer better integration with unusual sites, more flexibility on specification, and may offer better value on larger or complex shapes. Get at least three quotes and ask for photographs of comparable completed installations.
References (8)
Figures in this note were checked against the sources below on 2 October 2026. Superscript numbers in the text point to them. Every source the site cites, by topic.
- 1technicalvery strongThe National Archives (legislation.gov.uk), legislation.RN-J6L7TIThe primary legal text for garden rooms, sheds, summerhouses, pergolas, greenhouses and outdoor pools. Class E permits any building or enclosure, swimming or other pool within the curtilage required for a purpose incidental to the enjoyment of the dwellinghouse, plus a domestic heating oil container. Limitations: E.1(b) buildings, enclosures and containers other than the original dwellinghouse must not cover more than 50% of the curtilage; E.1(c) nothing forward of a wall forming the principal elevation of the original dwellinghouse; E.1(d) single storey only; E.1(e) maximum height 4 metres with a dual-pitched roof, 2.5 metres if any part is within 2 metres of a curtilage boundary, otherwise 3 metres; E.1(f) eaves no higher than 2.5 metres; E.1(g) not within the curtilage of a listed building; E.1(h) no verandah, balcony or raised platform; E.1(j) oil containers capped at 3,500 litres. E.4 defines incidental use as including keeping poultry, bees, pet animals, birds or other livestock for domestic needs or personal enjoyment, which is why a garden room used as a separate dwelling falls outside Class E.
- 2technicalvery strongThe National Archives (legislation.gov.uk), legislation.RN-Y7MVZKClass 7 is the conservatory and porch exemption every extension note leans on: the erection at ground level of an extension consisting of a conservatory, porch, covered yard or covered way, or a carport open on at least two sides, is exempt from the building regulations where the floor area does not exceed 30 square metres. Where a conservatory or porch is wholly or partly glazed, the glazing must still satisfy Part K4 and K5.1 to K5.4 and Part N of Schedule 1. Class 6 exempts small detached buildings up to 30 square metres single storey and up to 15 square metres otherwise, which is the garden room threshold.
- 3technicalvery strongMinistry of Housing, Communities and Local Government.RN-JYJ3I5The document that decides what electrical work a homeowner may legally do themselves, and the exact list of notifiable jobs. Regulation 12(6A), reproduced at paragraph 2.5, makes only three things notifiable: the installation of a new circuit, the replacement of a consumer unit, and any addition or alteration to existing circuits in a special location. Regulation 12(9) defines special location as, in a room containing a bath or shower, the zone extending vertically from finished floor level to 2.25 metres (or the shower head position if higher) and horizontally 600mm from the edge of the bath tub or shower tray. Paragraph 2.7 states that all other electrical installation work is not notifiable, namely additions and alterations to existing installations outside special locations, and replacements, repairs and maintenance anywhere. Paragraph 2.8 gives worked examples: a built-in cooker is not notifiable unless a new cooker circuit is needed, and connecting an electric gate or garage door to an existing isolator is not notifiable but running a new circuit from the consumer unit to that isolator is. Paragraph 2.2 confirms Part P reaches outdoor work including fixed garden lighting, pond pumps and outbuildings such as sheds, detached garages and domestic greenhouses. Notifiable work must be certified by self-certification by a registered competent person, third-party certification, or a building control body (paragraph 3.1), with the compliance certificate issued within 30 days (paragraph 3.4). Note that Approved Document P is a source of guidance rather than a ban: non-notifiable work still has to comply with BS 7671.
- 4technicalvery strongThe National Archives, legislation.RN-OWGIY3Schedule 2 Part 1 of the GPDO 2015, development within the curtilage of a dwellinghouse. This is permitted development itself: Class A enlargement and alteration, with the limits and conditions, through the classes covering roof alterations, porches, outbuildings and hard surfaces. Every statement about what can be built without planning permission traces to this Part, and the exclusions at the start of each class are where most projects actually fall out.
- 5technicalvery strongMinistry of Housing, Communities and Local Government.RN-L0FCJXThe in-force U-value tables a DIY insulation or door note must quote, with the exact numbers. Table 4.2, limiting U-values for new fabric elements in existing dwellings, sets roof 0.15, wall 0.18, floor 0.18, swimming pool basin 0.25, window 1.4 or Window Energy Rating Band B minimum, rooflight 2.2, doors with more than 60 per cent of the internal face glazed 1.4 or Doorset Energy Rating Band C minimum, and other doors 1.4 or Doorset Energy Rating Band B minimum. Table 4.3, for existing elements, gives a roof threshold of 0.35 and an improved value of 0.16, which is the figure a loft insulation note needs: paragraph 4.12 says a retained element whose U-value is higher than the column (a) threshold, for example through a loft or garage conversion, should be upgraded to the column (b) value. Paragraph 4.13 allows a lesser upgrade only where the improved value is not technically or functionally feasible or would not achieve a simple payback of 15 years or less. Paragraph 4.8 requires a replacement element to be no worse than the one it replaces as well as meeting Table 4.2. Paragraph 4.10 gives the heritage exception: where character must be maintained, a centre pane U-value of no more than 1.2 or low-emissivity secondary glazing. Note 9 records that the timber window concession of 1.6 or Band C ended on 14 June 2023. The 2021 edition came into force on 15 June 2022; a 2026 edition exists at https://assets.publishing.service.gov.uk/media/69c122a6cfa346b9d4704a55/ADL1_2026.pdf.
- 6costvery strongOfgem.RN-YYE8U2A price, true at 2026-09. The live source for any running-cost sum in a heating note. For 1 October to 31 December 2026 the direct debit cap is 26.32p per kWh for electricity with a 54.83p daily standing charge, and 7.97p per kWh for gas with a 29.68p daily standing charge, giving a typical annual dual fuel bill of £1,723, a 4% rise on the previous period. Ofgem states these are the average unit rate and standing charge for direct debit customers in England, Scotland and Wales; gas prices include 5% VAT while electricity carried no VAT in this period. The cap is reset every three months, so any note quoting a pence-per-kWh figure should be dated against this page.
- 7technicalvery strongHM Revenue & Customs, guidance.RN-9E4CJPHMRC's Capital Allowances Manual at CA22110, on shelters, huts and similar structures. Explains when a structure of this kind is plant and when it is simply premises, which is the test applied to a garden office, workshop or store. HMRC's own internal guidance, so it is what an inspector is working from rather than an adviser's reading of it.
- 8technicalvery strongHM Revenue & Customs, guidance.RN-ASTH5UHMRC's Capital Allowances Manual at CA22010, on buildings and structures. Sets out that a building is not plant, so its cost does not attract plant and machinery allowances, and identifies the list of assets treated as part of a building. The page that decides whether a landlord's spend on a property is relief now or relief much later, which is a different question from whether it is repairs or improvement.
-
The Town and Country Planning (General Permitted Development) (England) Order 2015, Schedule 2, Part 1, Class E, The National Archives, accessed 30 September 2026. legislation.gov.uk
-
The Building Regulations 2010, Schedule 2: Exempt buildings and work, The National Archives, accessed 30 September 2026. legislation.gov.uk
-
Approved Document P: Electrical safety - Dwellings (2013 edition), HM Government, accessed 9 September 2026. assets.publishing.service.gov.uk
-
The Town and Country Planning (General Permitted Development) (England) Order 2015, Schedule 2, Part 1, The National Archives, accessed 14 September 2026. legislation.gov.uk
-
Approved Document L, Conservation of fuel and power, Volume 1: Dwellings, 2021 edition incorporating 2023 amendments, HM Government, accessed 29 September 2026. assets.publishing.service.gov.uk
-
Energy price cap unit rates and standing charges, Ofgem, accessed 30 September 2026. Priced at 2026-09 and left there. ofgem.gov.uk
-
CA22110 - Plant and Machinery Allowances (PMA): buildings and structures: shelters, huts and so on, HM Revenue & Customs, accessed 7 September 2026. gov.uk
-
CA22010 - Plant and Machinery Allowances (PMA): buildings and structures: buildings, HM Revenue & Customs, accessed 7 September 2026. gov.uk